


Revenue came in at $24.4 billion, up 39% year over year. The growth was driven almost entirely by volume in Mounjaro and Zepbound. Mounjaro alone did $10.7 billion in the quarter, up 65%. Zepbound added another $5.3 billion, up 49%.
They raised full-year 2026 revenue guidance by $5.5 billion at the midpoint to a range of $91–92 billion. Underlying non-GAAP EPS guidance was also lifted, though heavy acquired IPR&D charges of $4.57 per share from the AtaiBeckley and other deals pulled the reported numbers lower.
Gross margin held up well at nearly 84%. The company continues to invest heavily in manufacturing and R&D while still expanding the commercial footprint of the incretin franchise.
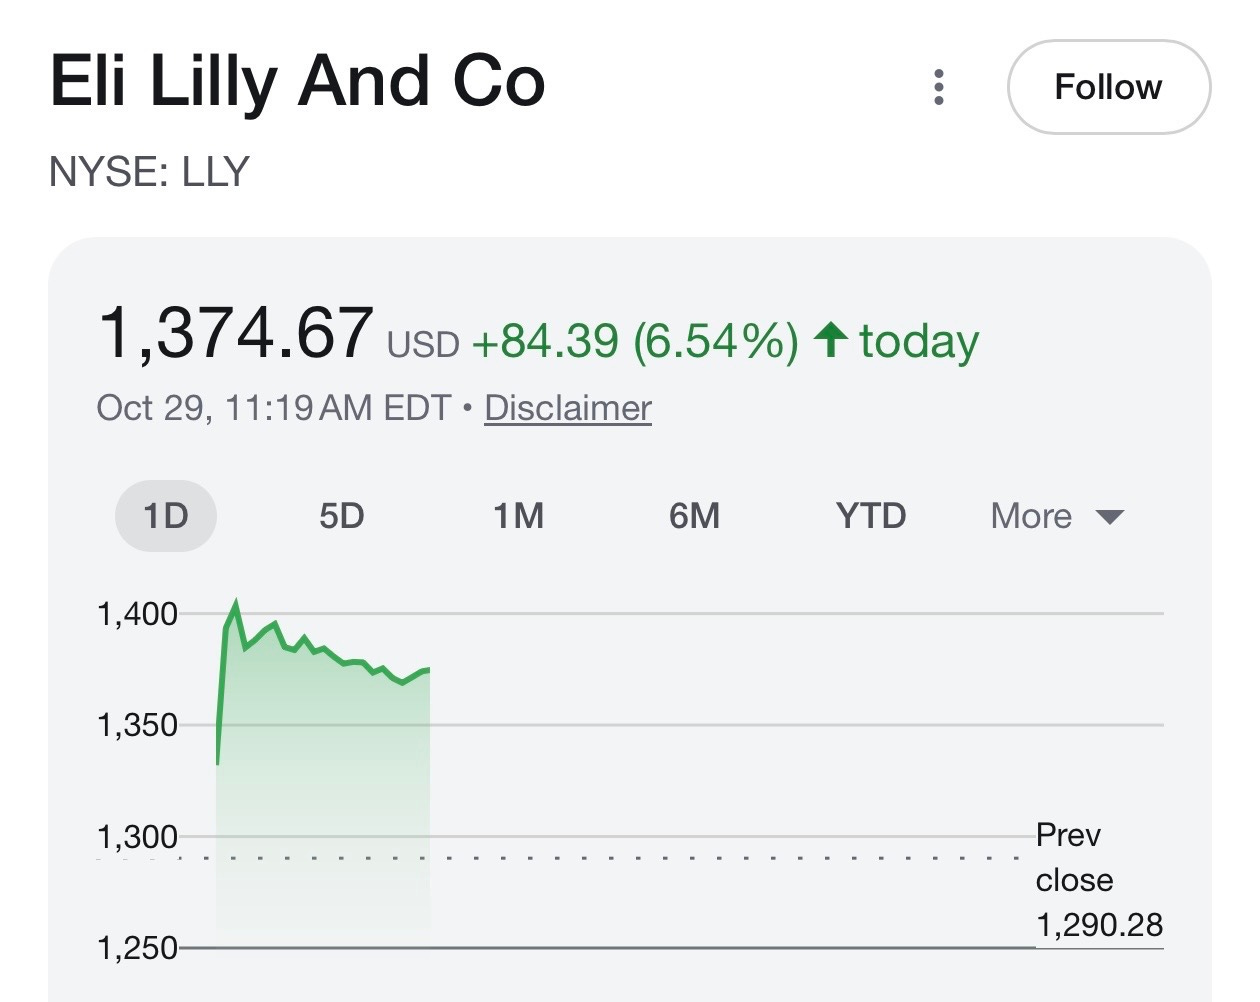
On the regulatory side they picked up several new approvals and label expansions, including Mounjaro for cardiovascular risk reduction in type 2 diabetes. Pipeline updates included strong head-to-head data for retatrutide versus Ozempic.
The core obesity and diabetes franchise is still compounding at a high rate. The rest of the portfolio (oncology, immunology, neuroscience) is growing fast from a smaller base. The large IPR&D charges are one-time in nature and do not change the underlying earnings power.
For now the thesis remains intact: dominant position in a market that continues to expand, with multiple shots on goal behind the current products. I’m holding tight and will keep adding on a regular basis.
Thanks for reading
FJ