


I spent time mapping the Pershing Square ecosystem properly.
There is the public company, Pershing Square Inc. (PS).
There is the operating manager, Pershing Square Capital Management.
And there are the funds: PSH, PSUS, the private vehicles, and the advisory relationship with Howard Hughes.
The only one that owns the fee streams is PS, ticker symbol $PS.
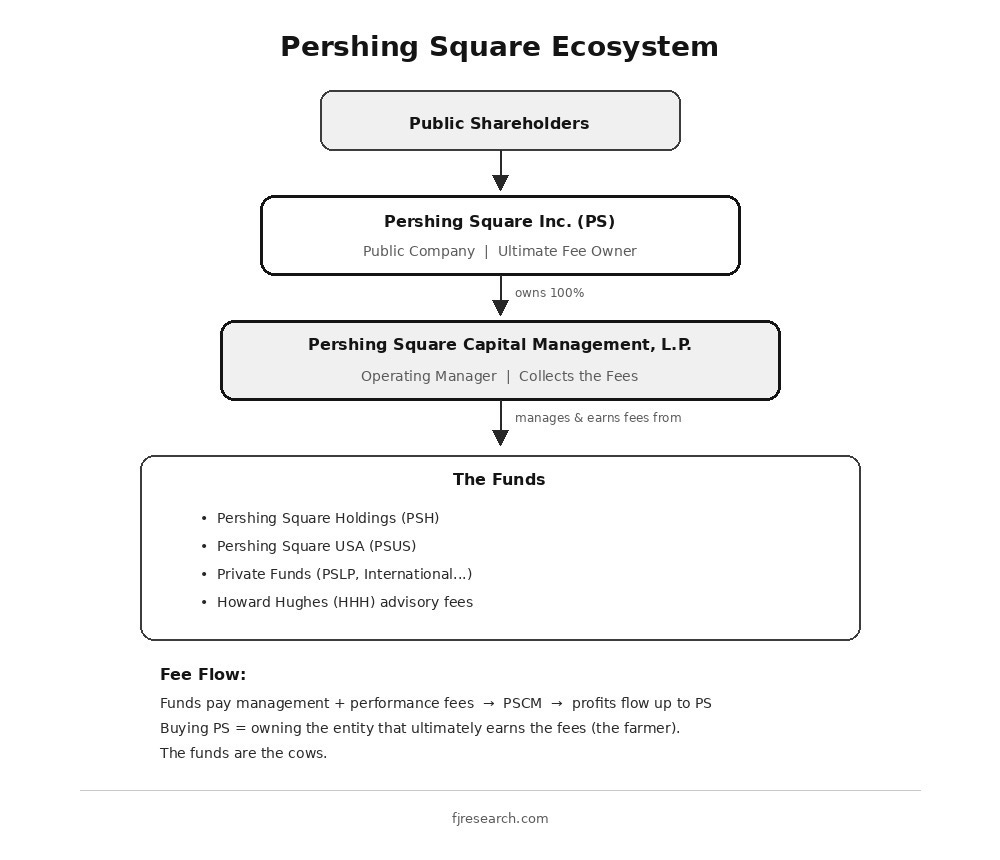
The funds pay management fees and performance fees to the manager. The manager is a wholly owned subsidiary of PS. So when you buy PS shares you are buying the entity that ultimately collects every dollar of those fees. That is the farmer. The funds are the cows.
I would not buy PSH. I would not buy PSUS. I would not buy HHH as a way to get exposure to Ackman & Ryan. Those are the fee-paying vehicles & PS is the ultimate fee collector.
The firm itself
Pershing Square runs roughly $33–35 billion with about 48 people. That is an absurdly lean structure. Ryan Israel has become the most important person after Ackman. He is CIO and clearly the number two. The culture is one firm, one P&L. There are no hundreds of analysts eating what they kill in separate silos. It is a small group that lives and dies together on the overall result.
Ackman has said publicly that every single employee owns multiple millions of dollars of equity in the company. That includes the receptionist and the people who clean the office. When the firm went public, those people became multi-millionaires. The firm claims it has not had an undesired departure in a long time. People stay. They grow old there. That is kind of unique on Wall Street and it tells you something about the internal culture.
Ackman can be criticized in many ways. The way the SPAC (Tontine Holdings) was handled was terrible…I lost some $$$ too. He has a tendency to talk too much and sometimes the narrative gets ahead of the results. Those are fair points & I am not writing a love letter ;)
What I am saying is that as someone who values lean structures, real and deep equity alignment, and a culture where people stay for decades, this is one of the more interesting setups in the public markets right now and especially in the asset management industry.
Why PS
This is the entity where Ackman, Ryan Israel, and the senior team have the majority of their personal wealth. They own the majority of the stock. Their incentives are aligned with long-term owners of PS, not with the limited partners in the funds.
They will launch new products & they will find ways to raise more permanent capital. Starting from a smaller base than the Apollos and KKRs of the world, AUM growth can still move the needle meaningfully.
Below $45 the risk-reward looks reasonable. I think mid-to-high teens compounding over the next cycle is achievable if they execute. No guarantee, no moonshot but a high-quality, internally diversified capital allocation business with a unique culture, deep skin in the game & ownership by the people running it.
Thanks for reading!
FJ